Although private equity investors use IRR and MOIC (IRR vs MOIC) to analyse the performance of their investments, the two metrics ask different questions about the success of a deal, which is why it’s important to understand the difference between IRR and MOIC to read the returns correctly. MOIC relates to the number of times the invested capital has been repaid, whereas IRR reflects the annualised rate of return taking into consideration the timing of cash flows. This guide goes beyond the definitions to explain how each of these metrics is really being measured and meaningfully interpreted in the field.
What Is IRR in Private Equity?
IRR, or Internal Rate of Return, is the annualised return a private equity investment makes over its holding period, taking into account each dollar invested and returned, and when it moved. IRR can also be particularly useful for comparing investments with differing life spans, such as comparing a two-year agreement to a seven-year agreement — even if the agreement returns appear to be similar, they may be very different once time is considered.
In essence, IRR can be used to solve one particular problem: what is the annualised rate of return where the present value of the cash inflows and outflows are equal? IRR is not based on the division of the profit by years but is actually a discount rate, as it comes from the solution of an equation; the IRR is therefore usually calculated using financial modelling tools and not by hand.
IRR Formula
IRR is defined as the discount rate that makes the net present value of all cash flows equal to zero:
0 = Σ [ CFₜ / (1 + IRR)ᵗ ] for t = 0 to n
Where:
- CFₜ = cash flow at time t
- IRR = internal rate of return
- t = time period
- n = final period
Most private equity professionals are not likely to solve this equation by hand in practice. The iteration is performed through the use of spreadsheet functions: IRR is the function used if cash flows happen at regular intervals (e.g. annual cash flows); XIRR is the function used for cash flows that fall on irregular days (e.g. in real transactions, capital calls and interim payments are made on different days, and the exit occurs at an irregular time).
Simple IRR Example
Consider a private equity investment with a single entry and a single exit:
| Year | Cash Flow |
| 0 | -$1,000,000 |
| 1 | $0 |
| 2 | $0 |
| 3 | $1,728,000 |
In this case, 1,000,000 is invested at the beginning of the year and nothing is distributed until the exit in Year 3 when 1,728,000 is received. The net present value of these cash flows is a function of the discount rate; its zero value yields an IRR of about 20%. The result is intuitive: $1,000,000 growing at 20 per cent a year for three years will be about $1,728,000. The key is that all of the value is received in one lump sum, three years from now; if the same $1,728,000 had been paid out over five years, the IRR would be significantly lower, but the dollars returned would remain the same.
Why Holding Period Matters
IRR is different from a return multiple. This investment multiple can yield vastly different IRRs depending on the time period involved. Suppose you have two possible scenarios where the investments yield a 2.0× MOIC.
- 2.0× MOIC realised over 2 years
- 2.0× MOIC realised over 5 years
This is because if the amount of money is invested for a period of two years, it implies a higher rate of return per year compared to doubling it over five years, as the money will be put to use sooner. The two-year outcome gives an IRR of around 30%, and the five-year outcome gives an IRR closer to 15%. The difference in this case is the identical multiple, very different annualised return, which establishes the central comparison at the heart of IRR vs MOIC.
What Is MOIC?
MOIC, or multiple on invested capital, is the number of times the invested capital has been returned to the investors. It is computed without respect to time, and hence is easy to share: If an investor put in $10, and returned $12.50, they would have experienced a 2.5× MOIC. It’s that ease of use that makes MOIC so popular in deal summaries; it’s just one number that everyone understands.
MOIC Formula
MOIC = Total Value Returned ÷ Total Capital Invested
Depending on the context and modelling convention, the numerator may incorporate realised proceeds, unrealised value, or both. For a simple realised investment:
$2 million proceeds ÷ $1 million invested = 2.0× MOIC
Simple MOIC Example
Consider a fund that invests $5 million and eventually receives total proceeds of $12.5 million:
MOIC = $12.5 million ÷ $5 million = 2.5×
Investors’ returns were 2½ times their actual investment. That figure alone isn’t a representation of whether the investment was good or bad; it depends on how long the investment was held, the risk taken to get that return, any distributions the fund made while holding the investment, the type of investment strategy the fund used, the relevant benchmark, and the fund’s goals and objectives.
What MOIC Does Not Tell You
MOIC does not directly communicate the duration of the investment, when distributions were made and how many, the annualised rate of return, or the time value of money. This is one of the most important differences between IRR vs MOIC: Both 3.0× MOICs are the same in absolute terms, but one is the annualised performance over three years, and the other is the annualised performance over 10 years.
IRR vs MOIC: What’s the Difference?
The table below summarises how the two metrics diverge:
| Metric | IRR | MOIC |
| Measures | Annualised rate of return | Multiple of invested capital |
| Considers timing | Yes | No |
| Considers holding period | Yes | No |
| Easy to understand | Moderate | High |
| Useful for | Return-rate comparisons | Total value creation |
| Sensitive to cash-flow timing | Yes | No |
| Common PE use | Deal/fund performance | Investment multiple |
What’s important to note: MOIC shows you the amount of money that was generated against the dollar invested, whereas IRR shows you the time it took to make that money. They are not mutually exclusive, however, as they cover each other’s weaknesses, and therefore private equity professionals don’t often talk about one without the other.
Why Can Two Deals Have the Same MOIC but Different IRRs?
This is the question that lies at the heart of how private equity professionals are using these metrics on a day-to-day basis. Suppose you have two investments: one that you make with $2,000 that you hold for 10 years and another one that you invest with $2,000 that you keep for 15 years.
Investment A
- Initial investment: $10 million
- Exit proceeds: $20 million
- Holding period: 3 years
- MOIC: 2.0×
Investment B
- Initial investment: $10 million
- Exit proceeds: $20 million
- Holding period: 6 years
- MOIC: 2.0×
| Investment | Initial Capital | Exit Proceeds | Holding Period | MOIC | Approx. IRR |
| Deal A | $10M | $20M | 3 years | 2.0× | ~26% |
| Deal B | $10M | $20M | 6 years | 2.0× | ~12% |
Both deals have a 2.0x MOIC, but Investment A has a much higher IRR as the capital is repaid in half the time. In reality, there are cash flows throughout the investment period, but for simplicity, these figures are based on a one-investment, one-exit cash flow. Two deals that are both expected to double an investment, say in five years, can be different by 10% in annualised return, and that still makes a difference in the context of a private equity firm, where quicker capital returns will give the firm more capital to invest in another business.
Which Metric Matters More to Private Equity Firms?
Neither metric is universally more important; they provide different information and are generally more useful together.
Investment Committee
IRR is generally one of the factors taken into account by investment committees, often along with expected MOIC, entry valuation, exit assumptions, leverage, projected cash flow, downside scenarios and anticipated holding period. The strength of return as well as the pace of it all is a part of whether a deal passes the committee’s bar or not.
LP Reporting
In general, Limited Partners will consider a variety of metrics when evaluating a fund, such as IRR, MOIC, DPI, TVPI and RVPI. Investors require both size and timing information: Investors should be wary of a fund with a good MOIC but an average IRR, because it may be locking up capital longer than they would like, while a solid IRR early in a fund’s life doesn’t necessarily mean that the multiple will remain high.
Deal Comparison
IRR can help compare investments based on various expected holding periods on an annualised basis, and MOIC can help investors determine the total value creation per invested dollar. Return metrics are always evaluated in the context of the risk taken and the assumptions on which they are based, rather than on their own as scorecards.
Other Private Equity Return Metrics
In addition to IRR and MOIC, there are a number of other metrics that are often used to measure a private equity fund’s performance.
DPI
Distributions to Paid-In Capital reflects cash actually distributed to the investors as opposed to paper value, in comparison to the capital contributed by investors.
TVPI
Total value to paid-in capital accounts for distributed value as well as the remaining, unrealised value of investments still held in the fund.
RVPI
Residual Value to Paid-In Capital is the remaining value of the portfolio versus the amount contributed; in other words, the unearned piece of UVPI.
| Metric | What It Measures |
| IRR | Annualised return based on cash-flow timing |
| MOIC | Total multiple on invested capital |
| DPI | Distributed value relative to paid-in capital |
| TVPI | Total value including realised and unrealised value |
| RVPI | Remaining unrealised value relative to paid-in capital |
It should be noted that while the level data and its interpretation can vary slightly from context to context, it is important to understand which basis a reported level reflects before comparing between funds.
Example of a Private Equity Return Calculation
Think about a more holistic hypothetical deal. A private equity firm gives a portfolio company $20 million and sells it for $50 million after four years without any dividends paid.
MOIC = $50M ÷ $20M = 2.5×
Solving for the annualised rate of return across this single entry and single exit produces an approximate IRR of 25.7%.
| Year | Cash Flow |
| 0 | -$20M |
| 1 | $0 |
| 2 | $0 |
| 3 | $0 |
| 4 | +$50M |
MOIC Interpretation: The fund generated 2.5 times the initial investment.
IRR Interpretation: Under these simplified cash-flow assumptions, the investment generated an annualised return of approximately 25.7%.
Real estate private equity deals are seldom this simple. Real deals can be interim dividends, recaps, follow-on investments, partial exits and many payments on multiple dates. In the real world, there may be many cash flows on uneven dates, and so it’s tempting to use functions such as XIRR, rather than just a single formula that could be solved by hand.
How Return Metrics Fit Into the Private Equity Investment Process
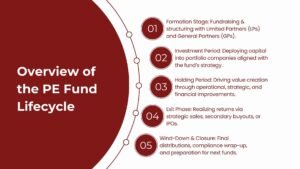
Analysis doesn’t occur just after a deal closes — return analysis is a part of the private equity investment process, from initial sourcing to final performance evaluation. The typical sequence is as follows: Deal Sourcing, Initial Screening, Due Diligence, Financial Modelling, Investment Committee Review, Acquisition, Portfolio Management, Exit and Performance Evaluation.
IRR and MOIC are used long before an investment is made. Private equity financial modelling training is used in deal economics and financial modelling to predict potential outcomes under a variety of assumptions prior to funding a deal, wherein the teams of professionals that look after underwriting and financial modelling come up with expected IRR and MOIC. The importance of modelling carefully, rather than assuming one base case for valuation on entry, revenue growth, EBITDA trajectory, leverage, ability to repay debt, exit multiple and holding period cannot be overstated as it can significantly impact a private equity investor’s return on investment throughout the private equity investment process.
How Financial Modelling Supports IRR and MOIC Analysis
It is financial modelling that links operating assumptions to investment returns. A well-designed leveraged buyout model integrates all of the above components into one model to determine IRR and MOIC.
That structure allows investment professionals to test how changes in individual assumptions affect expected private equity returns:
- Higher entry valuation → Lower expected returns
- Higher EBITDA growth → Potentially higher exit value
- More leverage → Potentially higher equity returns, but also greater financial risk
- Longer holding period → Potentially lower IRR even if MOIC remains unchanged
These scenarios are run before the dollars are put at risk, and not relying on IRR and MOIC as backwards-looking scorecards is what makes them forward-looking decision tools.
What Can Cause IRR and MOIC to Change?
Entry Valuation
A higher purchase price for the same exit value will yield lower multiples and annualised returns.
EBITDA Growth
Good operating performance has a positive effect on exit value, boosting both MOIC and IRR.
Leverage
Debt can enhance returns on equity by lowering the amount of equity risk required at the start, but it also heightens financial risk, and it can magnify losses in a downside situation.
Exit Multiple
The valuation multiple used at exit (e.g. market conditions, company-specific reasons) may have a significant impact on MOIC and IRR.
Holding Period
With the same proceeds at the end of the investment period, the longer the holding period, the lower the IRR, while the MOIC remains the same.
Interim Distributions
With distributions received earlier in the holding period, IRR is better even though the total amount distributed is equal to a later, lump-sum alternative.
Practical IRR vs MOIC Decision Framework
The more experienced investor usually goes through a brief string of questions, not one number.
Ask 1: How much value was created?
Look at MOIC.
Ask 2: How quickly was the value created?
Look at IRR.
Ask 3: How much cash has actually been distributed?
Look at DPI.
Ask 4: How much total value has been generated, including unrealised value?
Look at TVPI.
Ask 5: How much value remains unrealised?
Look at RVPI.
These five questions can be used together to provide a more comprehensive picture of performance than any one question can alone.
Conclusion
IRR and MOIC are two different ways of looking at private equity performance: MOIC is the multiple of capital generated, and IRR is an annualised return, which accounts for the timing of cash flows. Even when the underlying multiple is the same, as will be seen in the examples throughout this guide, there are significant differences between the two metrics. Both measures are not to be taken on their own — DPI, TVPI and RVPI provide more context to how a professional would look at the performance of a fund and they complete the picture when combined with IRR vs MOIC to understand how the private equity investment proces measures and communicates results. .
Professionals who understand both the calculation and interpretation of these metrics, and who can connect them to the underlying financial model, are better positioned to evaluate investment opportunities and communicate private equity returns clearly to colleagues and investors alike.
Constructing a real fluency with IRR, MOIC, and the general mechanics of returns on deals requires doing more than simply memorising the formulas; they must be understood in the context of the underlying model. Training in structured private equity valuation and financial modelling is a useful tool for analysts, associates and finance professionals seeking to improve these skills in the creation of entry valuations, leverage assumptions and exit scenarios, as well as investor cash flow.